
A hailstorm can leave a roof looking mostly normal from the driveway while damaging shingles, vents, flashing, and gutters above. That is why a clear roof claim example can help Colorado homeowners understand what happens between the storm, the inspection, the adjuster visit, and the finished repair.
A good claim is not about making damage sound worse than it is. It is about documenting real storm-related damage, understanding your policy, and presenting the needed repairs clearly. No shortcuts. No surprises.
A Roof Claim Example After a Colorado Hailstorm
Imagine a homeowner in Colorado Springs experiences a fast-moving spring hailstorm. The next morning, they notice granules collecting near a downspout, several dents in the metal gutter, and a torn window screen. Their roof is 12 years old and has never leaked.
The homeowner should not assume that no leak means no roof damage. Hail can bruise or crack asphalt shingles and shorten their service life before water reaches the attic. On the other hand, not every mark on a roof is hail damage, and normal aging is usually not covered by a storm claim.
The homeowner begins by taking photos from the ground of the date-stamped storm alerts, dented gutters, damaged screens, and any fallen debris. They also make notes about the date, approximate hail size, and visible damage. Then they schedule a professional roof inspection.
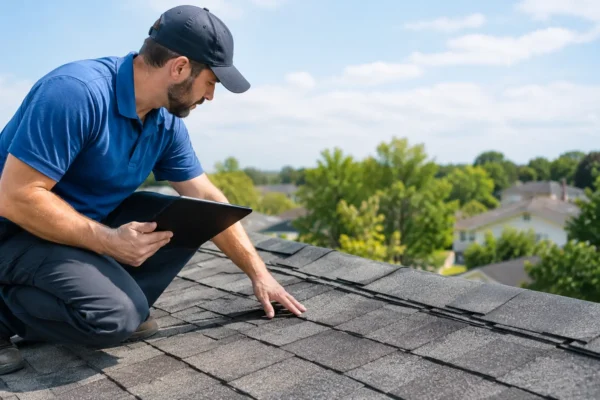
During the inspection, the contractor finds consistent hail impacts on multiple roof slopes, along with damage to ridge caps, soft-metal vents, and gutter components. The contractor also checks for common issues that affect the scope of repairs: lifted shingles, compromised flashing, damaged pipe boots, and code-related requirements that may apply during replacement.
With that information, the homeowner contacts their insurance carrier to open a claim. The carrier assigns a claim number and schedules an adjuster inspection. The homeowner provides the date of loss, a straightforward description of what they observed, and the photos they collected. They avoid guessing about the cause of every mark or promising a repair cost before the inspection is complete.
At the adjuster appointment, the contractor meets with the homeowner and adjuster to review the storm-related findings. The adjuster agrees that the roof has covered hail damage and prepares an initial estimate. The estimate includes removal of the damaged shingles, replacement shingles, underlayment items, labor, and several related components. It may also include payment for damaged gutters or other exterior items if those are covered and documented.
That is a realistic roof claim example: evidence is collected, damage is inspected, the insurer evaluates coverage, and the repair scope is reviewed before work begins. It is not a guaranteed outcome. Coverage depends on the policy, deductible, exclusions, roof age, prior damage, and the insurance company’s findings.
What the Initial Insurance Estimate May Mean
Homeowners are often surprised when the first insurance estimate does not match the full project price exactly. That does not automatically mean someone made a mistake. Insurance estimates are often written from photos, measurements, and visible conditions at the time of inspection. Some necessary items are only found once old materials are removed.
For example, the estimate may not include replacement of damaged decking because the decking could not be seen before tear-off. It may not include a code-related item until the contractor confirms that the local requirement applies. A contractor may also identify flashing, ventilation, or specialty materials that were missed in the original scope.
When that happens, the contractor can document the condition with photos and measurements, then submit a supplement for the insurer to review. A supplement is not an attempt to add unnecessary work. It is a request for consideration of legitimate, covered items that were not included in the initial estimate.
The homeowner still has a role to play. Read the estimate, ask what each line item covers, and compare it with the recommended scope of work. If something is unclear, ask before signing a contract or authorizing work. An honest contractor should be able to explain the difference in plain language.
How Deductibles Work in This Example
Suppose the roof replacement and related covered repairs total $18,500. The homeowner’s deductible is $2,500. If the claim is approved for the full covered amount, the insurance company generally pays the covered loss minus the deductible, subject to the policy terms.
The deductible is the homeowner’s responsibility. Be cautious if a contractor offers to waive, absorb, or hide it. In Colorado, deductible requirements and insurance practices matter, and attempts to disguise deductible payments can create legal and financial problems. A trustworthy contractor will explain the deductible clearly rather than making promises that sound too good to be true.
Actual cash value and replacement cost value policies can also pay differently. With an actual cash value policy, depreciation may be deducted based on the roof’s age and condition. With a replacement cost policy, recoverable depreciation may be released after the work is completed and required documentation is submitted. Your declarations page and claim representative can help clarify which coverage applies.
What to Document Before You File
A homeowner does not need to climb onto a roof to build a strong claim. In fact, walking on a damaged or steep roof can be dangerous and can cause further damage. Start with safe, simple documentation from the ground and let trained professionals inspect the roof.
Keep photos of exterior damage, including gutters, downspouts, siding, screens, windows, fence sections, and air-conditioning fins if they were affected. Save storm notifications, repair receipts, maintenance records, and previous roof documents if you have them. Record the date you discovered the damage and the date of the storm, if known.
It also helps to keep a simple claim file. Write down the claim number, the adjuster’s name, appointment dates, and any questions you need answered. Save copies of estimates and insurer correspondence. A little organization prevents confusion when there are multiple payments, supplements, or exterior repairs happening at once.
Common Mistakes That Can Weaken a Roof Claim
The most common mistake is waiting too long. Policies often require prompt notice of a loss, and storms can damage many homes at once. Waiting can make it harder to connect the damage to a specific event, especially after another season of wind, snow, and sun exposure.
Another mistake is filing a claim before anyone has inspected the roof. A professional inspection does not guarantee coverage, but it can help a homeowner decide whether there is enough evidence of storm damage to justify opening a claim. Filing claims for minor issues that fall below the deductible may not be the best choice for every household.
Homeowners can also run into trouble by signing broad paperwork without reading it carefully. Before you sign, understand whether it is an inspection authorization, a contract, or an assignment of insurance benefits. Ask who is responsible for communicating with the carrier, what happens if the claim is denied, and whether you can cancel under specific conditions.
Finally, do not choose a contractor based only on the lowest number or the loudest promise. After a major hailstorm, out-of-town crews often arrive quickly. Local accountability, proper licensing and insurance, clear communication, and a proven workmanship process matter long after the storm chasers leave town.
When a Claim Is Denied or Underpaid
A denial does not always mean the conversation is over. First, ask for the denial or estimate in writing and review the stated reason. The carrier may have found that the damage is wear and tear, below the deductible, excluded by the policy, or unrelated to the reported storm.
If you believe the inspection missed visible storm damage, request a reinspection and provide supporting documentation. Your contractor can explain the roof conditions they observed and supply photos, measurements, and a detailed repair scope. Stay factual and patient. The goal is an accurate assessment, not an argument.
There are times when a repair paid out of pocket makes more sense than continuing a claim. Small localized damage, an aging roof near the end of its life, or damage below the deductible can change the decision. A reliable contractor should tell you when a claim may not be worthwhile.
Get Clear Guidance Before You Commit
Storm damage is stressful because your roof protects everything beneath it. You should not have to sort through policy language, contractor proposals, and repair decisions alone. Tither Roofing and Construction helps local homeowners inspect storm damage, understand the repair scope, and coordinate with insurance carriers when a covered claim is appropriate.
If hail or wind has left you wondering what happened overhead, start with a professional inspection and an honest conversation. A clear answer today can protect your home from a much larger problem tomorrow.